In the first week of October, brokerage apps in Korea started pushing alerts about year-end pension deposit events. The message is simple: three months remain before year-end tax settlement (연말정산), so fill your pension savings account (연금저축) and IRP. But the pension account tax credit is not a machine that hands back KRW 1,485,000 the moment you deposit KRW 9 million. (As of October 2026 · last updated 2026-10-07)
What actually comes back depends on your salary band, last year’s final tax amount, and how you split the money between the two accounts.
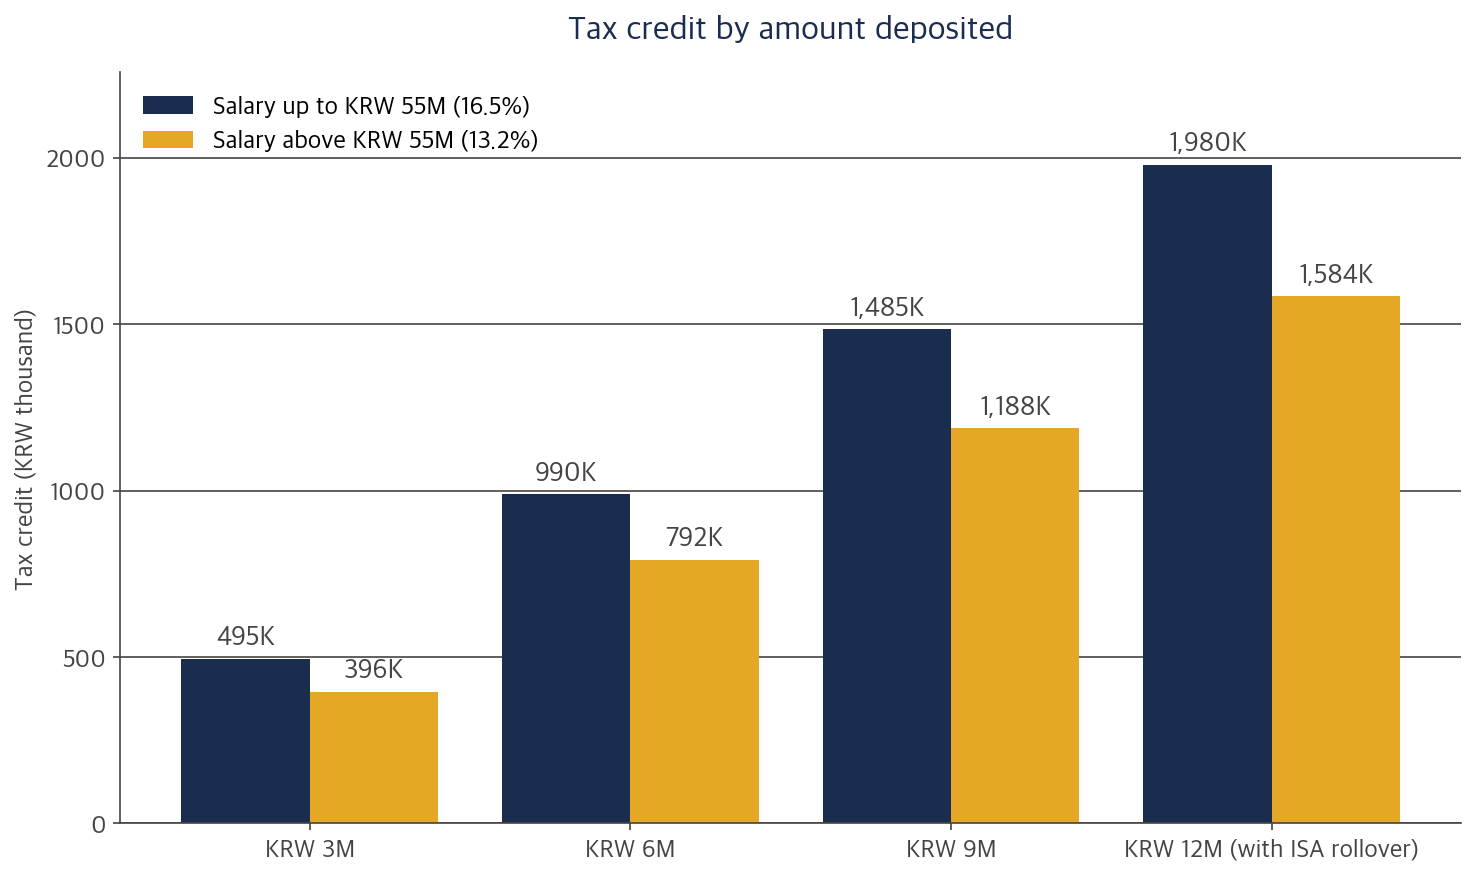
Bottom line: if you have spare money you can leave untouched until age 55, filling KRW 6 million in pension savings and KRW 3 million in an IRP before December 31 is the right call. With total salary of KRW 55 million or less, KRW 1,485,000 comes off your tax; above that, KRW 1,188,000.
The catch is that a tax credit can only cut tax you actually owe. If last year’s final tax amount (결정세액: income tax plus local income tax on your withholding receipt) was smaller than that, the full KRW 9 million will not bring the full amount back. Check the final tax amount first, then size the deposit to fit inside it.
The pension tax credit in 2026 comes down to four numbers
For deposits made this year, the tax credit covers up to KRW 6 million a year in a pension savings account and up to KRW 9 million combined once an IRP (Individual Retirement Pension, 개인형 퇴직연금) is added. The credit rate is 15% if your total salary is KRW 55 million or less (or comprehensive income of KRW 45 million or less), and 12% above that. Including local income tax, that is 16.5% and 13.2%.
The rules are in Article 59-3 of the Income Tax Act (소득세법) and the National Tax Service (국세청) guide to the pension account tax credit. Employee contributions to a DC-type company retirement plan count toward the same KRW 9 million as an IRP.
Two more things to keep in mind. Separately from the tax credit, the total you can deposit into pension savings and an IRP combined is KRW 18 million a year (Financial Supervisory Service pension portal, IRP guide). And only money actually credited to the account by December 31 counts for this year’s credit. Whether you spread it from October or deposit once in December, the credit is the same.
Three months left: how much goes into which account
Start by checking what you have already deposited this year. A pension savings account shows this year’s deposits in the app of the brokerage, bank or insurer where you hold it, and an IRP shows the same in the app of its provider. If your accounts are scattered across several firms, the Financial Supervisory Service (금융감독원) pension portal (My Pension lookup menu) lists every personal and retirement pension contract you hold in one place.
The credit limit is per person, so however many accounts you have, the combined cap is KRW 9 million.
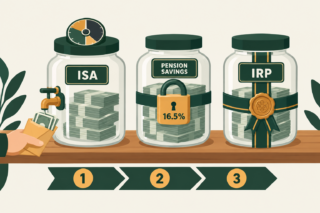
Fill the pension savings account first, up to KRW 6 million. Because pension savings only qualify for the tax credit up to KRW 6 million, putting all KRW 9 million into that one account leaves KRW 3 million uncredited this year. The remaining KRW 3 million has to go into an IRP, and an IRP can only be opened by someone with income in Korea (employees, the self-employed and people receiving severance pay included).
The reverse works: KRW 9 million in an IRP alone fills the whole limit. The fee and product differences between the two accounts are covered in the pension savings vs IRP comparison.
| Deposited so far this year | Left to reach KRW 6M (monthly, Oct·Nov·Dec) | Left to reach KRW 9M (monthly) | Credit at KRW 9M (16.5% / 13.2%) |
|---|---|---|---|
| KRW 0 | KRW 6M (KRW 2M a month) | KRW 9M (KRW 3M a month) | KRW 1,485,000 / 1,188,000 |
| KRW 1.5M | KRW 4.5M (KRW 1.5M a month) | KRW 7.5M (KRW 2.5M a month) | KRW 1,485,000 / 1,188,000 |
| KRW 3M | KRW 3M (KRW 1M a month) | KRW 6M (KRW 2M a month) | KRW 1,485,000 / 1,188,000 |
| KRW 4.5M | KRW 1.5M (KRW 500K a month) | KRW 4.5M (KRW 1.5M a month) | KRW 1,485,000 / 1,188,000 |
| KRW 6M (pension savings full) | KRW 0 | KRW 3M (IRP, KRW 1M a month) | KRW 1,485,000 / 1,188,000 |
The monthly figures assume three deposits in October, November and December; one lump sum in December earns the same credit. But every firm sets its own year-end cut-off time, and deposits piling up on December 31 can be delayed in processing, so finishing before the last week is the safer route. This is also the season when KB Securities and other brokerages run year-end net-deposit promotions through December 31.
Three cases where you do not get the full KRW 1,485,000 back
If you deposited KRW 9 million and the refund was smaller than expected, it is usually one of the three cases below. The tax credit itself does not shrink; either there is not enough tax for it to offset, or a lower rate applies.
- Your final tax amount is smaller than the credit: the tax credit is subtracted from your calculated tax and cannot push what you owe below zero. If the final tax amount (결정세액) on last year’s withholding tax receipt (원천징수영수증, also visible in Hometax under payment statements) was KRW 600,000 with income tax and local income tax added together, and you claimed no pension credit, then with similar income and deductions this year, roughly KRW 600,000 is the most the pension tax credit can cut. Deposit KRW 9 million and you get KRW 600,000 back, not KRW 1,485,000. If you claimed a pension credit last year, add that credit back before comparing, because the tax before the credit is the ceiling that matters this year (KB Asset Management guide).
- Your total salary exceeds KRW 55 million: the rate drops from 16.5% to 13.2%, so the credit on KRW 9 million is KRW 1,188,000. The gap is KRW 297,000. If bonuses are likely to push your total salary just past KRW 55 million this year, lower your expectation in advance.
- All KRW 9 million went into pension savings, or you are a foreign employee on the flat rate: the KRW 3 million above the pension savings cap is not credited this year. And a foreign employee who elects the 19% flat tax rate under Article 18-2 of the Restriction of Special Taxation Act (조세특례제한법) gives up the Income Tax Act’s exemptions, deductions, reductions and tax credits for that year, so the pension tax credit is not available either.
Uncredited deposits are not lost. Money that never received a tax credit is excluded from tax when you later withdraw it (NTS guide to the pension account withdrawal order).
Next year you can obtain a pension contribution tax credit confirmation (연금보험료 등 소득·세액공제 확인서) from Hometax, file it with your provider, and have the amount treated as that year’s deposit for the credit (KB Kookmin Bank guide to the conversion rule). The conversion only counts toward the year you apply, and accounts already paying a pension or with a partial withdrawal are not eligible.
If an ISA has matured, you have 60 days to add up to KRW 3 million of limit
Move the proceeds of a matured ISA (개인종합자산관리계좌) into pension savings or an IRP within 60 days and 10% of the amount moved, up to KRW 3 million, is added to that year’s tax credit limit (Mirae Asset Investment and Pension Center). The NTS notes that the extra limit applies only in the year the matured balance is deposited. The table shows the effect by amount moved.
| Amount moved from the ISA | Extra limit (10%, max KRW 3M) | That year’s tax credit limit | Credit if the limit is filled (16.5% / 13.2%) |
|---|---|---|---|
| KRW 10M | KRW 1M | KRW 10M | KRW 1,650,000 / 1,320,000 |
| KRW 20M | KRW 2M | KRW 11M | KRW 1,815,000 / 1,452,000 |
| KRW 30M or more | KRW 3M | KRW 12M | KRW 1,980,000 / 1,584,000 |
None of this happens automatically. Once 60 days pass after the maturity closure, the extra limit is gone, and money moved into a pension account becomes money you draw as a pension after 55. If your ISA matures in November or December, count the dates first: move it this year to lift this year’s limit, or move it in January inside the 60-day window to lift next year’s.
Either way it attaches to the year of the deposit. If you split the rollover across two years, the two years share the KRW 3 million extra limit, and the second year gets only what is left after the first year’s share (Article 59-3, paragraph 4 of the Income Tax Act). Your options after an ISA matures are laid out in the ISA account types guide.
The 2026 tax reform bill that the government finalised at the September 1 cabinet meeting would add rollovers from the new Productive Finance ISA (생산적금융 ISA) to this extra limit as well (Korea Tax Times outline of the bill). It is a government bill that still needs National Assembly (국회) approval, so this year’s decision runs on the current ISA rules only. The ISA side of the bill is covered in the Productive Finance ISA article.
What to do now if you want to fill the pension tax credit this year
My view: if your final tax amount is at least KRW 1,485,000 and you will not need the money before age 55, fill the KRW 9 million before December. A 16.5% tax credit is an amount fixed by law and taken off the tax of the year you deposit, and gains inside the account are not taxed until withdrawal. If your final tax amount is small or you will need the money soon, there is no reason to fill the limit. Here is how it splits by situation.
- You have already put KRW 6 million into pension savings: open an IRP and add KRW 3 million for another KRW 495,000 at 16.5%. Only people with income can open one, and an IRP does not allow early withdrawal without a statutory reason, so deposit only money you can leave until 55.
- You have deposited nothing this year: look at last year’s final tax amount (income tax plus local income tax) first. If you claimed a pension credit last year, add that credit back before comparing. If the result is around KRW 1 million, KRW 6 million in pension savings (a KRW 990,000 credit) is the right size, and filling KRW 9 million would cut only about KRW 10,000 more. If it was above KRW 1.5 million, the full KRW 9 million credit survives intact.
- The money is a home down payment or a buffer for a job gap within three to five years: do not deposit it. Break the account before 55 and the credited principal plus gains are hit with 16.5% other-income tax, which effectively hands the credit back (Financial Supervisory Service financial tip). Permanent emigration (해외이주) is on the NTS list of unavoidable reasons that lower the tax to 3.3% to 5.5% pension income tax if documents are filed within six months of the event, so ask your provider whether your departure qualifies before closing the account. If you still want to deposit, use only pension savings, which allow withdrawal, and run the numbers in the early withdrawal cost guide first.
- You are 34 or under and earn more than KRW 55 million: if the government bill passes as drafted, young savers get 15% on IRP and other retirement pension account deposits regardless of income from January 1, 2027. Pension savings deposits are not covered (Toss Bank summary of the bill). That is no reason to defer this year’s deposit: this year’s KRW 9 million limit simply expires. Next year’s benefit comes with next year’s limit, and this year’s share belongs in this year.
Three things to watch. First, the tax bill review in the December regular session of the National Assembly: the 15% youth IRP rate and the Productive Finance ISA rollover limit only apply from 2027 if passed, and the content can change in review. Second, the year-end deposit cut-off times each firm announces in December.
Third, whether this year’s deposits show up correctly in the simplified year-end tax settlement data in January. If they are missing, get a pension contribution certificate (연금납입확인서) issued by your provider and hand it to your employer.
The most common misjudgment is treating “deposit KRW 9 million, get KRW 1,485,000 back” as a fixed number. A refund is the difference between tax already withheld and the final tax amount, and the pension tax credit cannot push the final tax amount below zero.
Someone with a modest salary or many other deductions, and therefore a small final tax amount, gets back only that amount no matter how much they deposit. The starting point for sizing the deposit is the final tax amount (income tax plus local income tax) on your own withholding receipt, not the KRW 1,485,000 in the advertisement.
Your final tax amount, not the advertisement, sets the refund
The pension tax credit is one of the few tax decisions that has to be finished inside the calendar year. Only deposits credited by December 31 count and an unused annual limit does not roll over, so checking the final tax amount and deciding the deposit is an October task, not a December one. To review the other deduction items alongside it, see the year-end tax deductions checklist.
- Tax credit on up to KRW 6 million in pension savings and KRW 9 million including an IRP, at 16.5% or 13.2% depending on whether total salary exceeds KRW 55 million
- The ceiling is this year’s final tax amount; estimate it from last year’s receipt (income tax plus local income tax), and KRW 9 million is not always KRW 1,485,000
- Pension savings first up to KRW 6 million, the remaining KRW 3 million into an IRP, credited by December 31
- Matured ISA money moved within 60 days adds 10%, up to KRW 3 million, to the limit
- Do not deposit money you will break before 55; early closure costs 16.5% on credited principal and gains
Related reading
- Pension Savings vs IRP: 5 Essential Differences You Must Know
- Tax-Advantaged Account Withdrawals in Korea: What Closing an ISA, Pension Savings or IRP Early Costs
- 15 Essential Tax Deductions You Can’t Afford to Miss: Year-End Checklist
Disclaimer: This article is for information only and is not a recommendation to open any financial product or personal tax advice. The pension account tax credit limits, rates and refund figures reflect the Income Tax Act and National Tax Service (국세청) guidance as of October 7, 2026, and the 2026 tax reform bill is a government proposal still under National Assembly review. Before depositing, check the latest guidance on Hometax and with your account provider. All decisions are your own responsibility.